
How to Pay Off Your Mortgage Before You Retire
If you're in your 50s and still carrying a home loan, you've probably done a quiet calculation. You've worked out the year the loan ends, and it lands well after the year you want to stop working.
That's the problem worth solving. Not the rate. The gap between when your mortgage ends and when your income does.
This is about how to pay off your mortgage before you retire when you're already 10 or 15 years in. Most advice on this is written for someone signing a brand new loan. You're not that person. Your situation is different, and in one important way it's better than you think.
You've already done the maths. So why haven't you acted to pay off your mortgage before you retire?
Most people I work with knew their mortgage would outlive their career years before they did anything about it. They'd run the numbers. They knew the loan ran past the day they wanted to stop. And still, nothing moved.
That used to puzzle me, until I remembered research I co-authored years ago, back when I worked inside the banks.
We had a theory that people didn't switch banks because switching was a hassle. So we tested it. We offered to do the entire switch for people. Close the old accounts, move the payments, waive the fees. Almost no one took it up.
The hassle was never the real barrier. What stopped people was doubt, distrust, and a quiet sense that it could wait.
The same thing sits on top of every mortgage decision. You already know the loan outlives the career. What holds you still is the worry that you'll get it wrong, or that the last broker oversold you, or that there's a catch. So it waits. And time, the one thing you can't get back, keeps moving.
If that's you, it's not a failing. It's the most normal response there is. It's worth naming, because you cannot fix a problem you keep postponing.
Where you actually stand, 10 to 15 years in
Here's the part most people get wrong, and it matters.
By the time you're 10 or 15 years into a 30-year loan, you've already paid the expensive part. Early in a loan, almost every repayment is interest. Those years are behind you. You've handed them over, and you can't get them back.
But look at the balance. On a standard 30-year loan, 13 years in, most people have cleared less than a third of what they borrowed. So you've paid the dear years, and you still owe most of the money.
That sounds brutal, but it's also the opportunity. The expensive part is done, and the back half of the loan is where the balance actually falls.
None of this is a trick the bank played on you. A loan charges interest on what you still owe, so early on, when you owe the most, most of the payment is interest. That's how the maths works. But it means the longer a large balance sits there, the more it costs you.
The structure works against you the longer you wait, and no one's coming to change it for you.
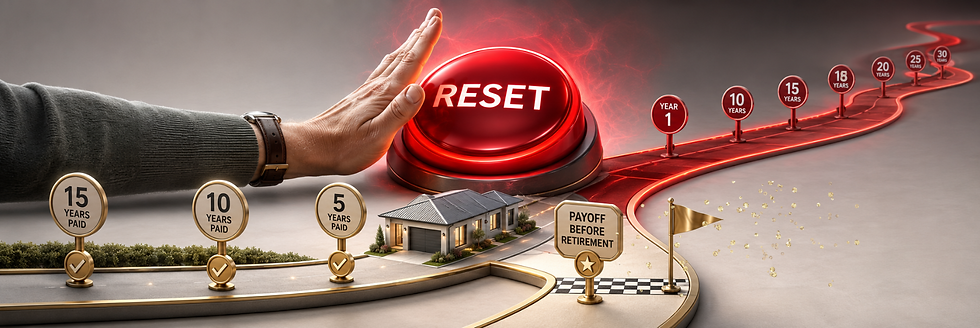
The trap that sends you back to the start
Here's where good intentions go wrong:
You go looking for a sharper rate
You refinance
And the new loan quietly resets to a fresh 30-year term
Lower rate, longer runway
It feels like a win
It's not.
You've taken a balance you already carried through its most expensive years and stretched it back out to 30. You'll pay interest on it into your 70s or 80s. You pay for the same debt twice.
A lower rate on a longer term can cost you more than a higher rate on a term that ends when you need it to.
The rate is not the thing. The term is the thing.
The one change that clears the loan: set the payoff date yourself
Stop letting the loan set your end date. Set it yourself.
Pick the year your income stops. That's your deadline. Then build the mortgage backwards from it.
In practice that means a few things working together:
Hold a loan term that ends when your salary does, not 15 years after
Aim every surplus dollar at the remaining balance, not at a longer, more comfortable schedule
Run your income and savings through a full offset, so your own cash works against the balance every day it sits there
Where a bigger move is on the table, like how your super fits in as you approach retirement, coordinate that with your financial planner. That part sits with them, not with me.
Done together, these reverse-engineer the repayment to hit your retirement date. The loan stops being an open-ended commitment and becomes a countdown you control.
This is not a rate problem
Rates move. Your loan term doesn't, unless someone changes the structure. Chasing the cheapest rate while ignoring the term is how people end up retired with a mortgage still running.
The clients I work with don't want a slightly better rate. They want the loan gone before the salary stops, without selling the house or giving up the life they've built. That's a structure and timing job, and it's the one I do.
Start with the numbers
If you're 10 or 15 years in and the loan's on track to outlive your career, the worst move is the one most people make.
Nothing.
You've already paid the expensive part. The back half is winnable, but only if you aim at it deliberately.
What now
If your mortgage is set to run past the day you want to retire, that's worth a conversation. We start with your numbers and your timeline, and go from there.
**This is general information, not personal or financial advice.


Comments